
Non-Medical Home Care Business Insurance

Combined Professional & General Liability from $42 per month
Covers claims if a client gets hurt in your care
Insurance is often required depending on your state
Based on 800+ Google reviews

Compare Quotes
From multiple carriers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Coverage
Delivered to your inbox
Compare Quotes
From multiple carriers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Coverage
Delivered to your inbox
Compare quotes from our trusted insurance partners:

On this page:
What does non-medical home care business insurance cover?
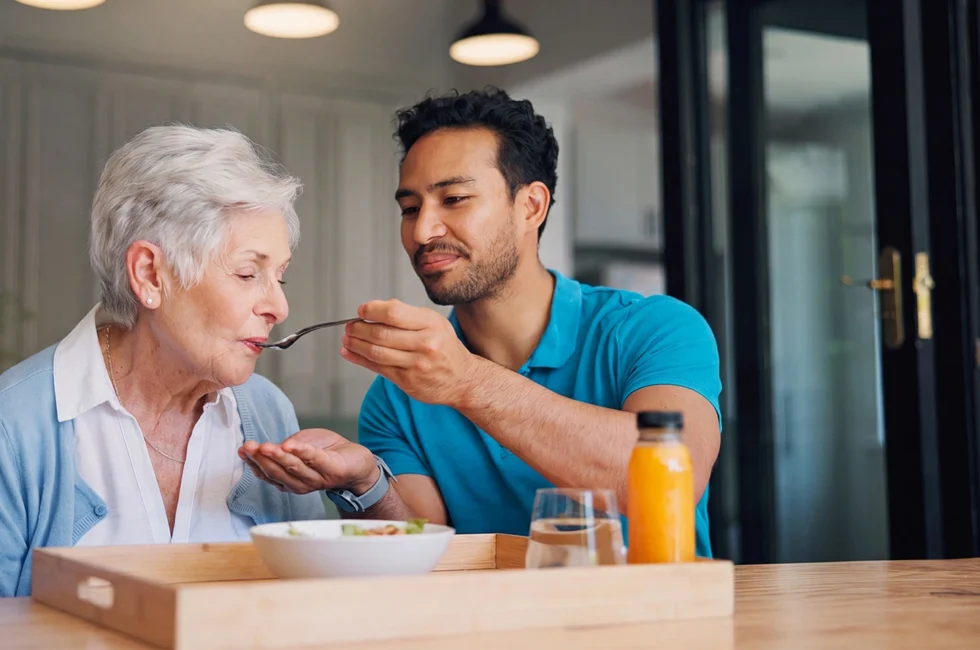
Non-medical home care business insurance helps protect home care agencies and independent caregivers from the cost of risks associated with providing in-home support services. Common risks include:
- Client injury and negligence claims
- Accidental damage to a client’s property
- Third-party bodily injury claims
- Employee workplace injuries
- Cyberattacks and data breaches involving client information
BizInsure understands the insurance needs of non-medical home care businesses. Compare quotes, choose coverage, and buy online—all in minutes.
Why do non-medical home care businesses need insurance?
Non-medical home care businesses may need insurance to help cover the cost of claims, lawsuits, and other unexpected expenses. Workers’ Compensation insurance is required in most states for businesses with employees. Many agencies may also choose Professional Liability and General Liability insurance to help protect their business.
Providing care in a client’s home comes with unique responsibilities. From assisting with personal care and mobility to companionship and household support, your employees work in environments that you don’t always control. Insurance can help protect your business from the financial impact of client injuries, property damage, employee injuries, and other unexpected incidents that can arise while delivering care.
What types of insurance do non-medical care providers need?
BizInsure bundles Professional Liability and General Liability into one policy for non-medical care providers.




Fast, simple, and convenient
Start a quote to see how much you can save and buy online in minutes.
How much does non-medical home care liability insurance cost?
General liability insurance for non-medical home care businesses starts at $42.31 per month. Combined professional and general liability coverage starts at $42.31 per month.
Factors influencing cost
- Risks of the industry
- Coverage level amount
- Annual turnover
- Number of employees
- Claims history
The pricing information on this page is general in nature and provided for illustrative purposes only. It does not take into account your specific circumstances, business operations, or risk profile. Actual premiums vary based on your profession, location, claims history, and other factors.
Get flexible coverage to match your needs
Choose from flexible coverage levels to fit your unique non-medical home care business.
Factors influencing cost
- Risks of the industry
- Coverage level amount
- Annual turnover
- Number of employees
- Claims history
The pricing information on this page is general in nature and provided for illustrative purposes only. It does not take into account your specific circumstances, business operations, or risk profile. Actual premiums vary based on your profession, location, claims history, and other factors.
Get flexible coverage to match your needs
Choose from flexible coverage levels to fit your unique non-medical home care business.
Unsure how much to choose? Think about:
- Statutory professional requirements
- Coverage required by contracts
- Number of employees being covered
- Your contract value
- Worst case scenario claim size
Frequently asked questions
Per-occurrence and aggregate limits both refer to the maximum payout of an insurance policy, but in different settings.
Per-occurrence limits are the maximum amount a policy will pay for any one incident or claim. Aggregate limits are the maximum amount that will be paid over the duration of the policy.
Fast, simple, and 100% online
Get instant coverage in under 10 minutes. Just 3 easy steps!
Enter Occupation
Search & select your occupation
Choose Coverage
Select the coverage you need
Get Covered
Instant certificate of insurance and policy documents in your inbox

Small business insurance experts
We are proud of our innovative insurance platform, outstanding team, and stellar workplace that have helped aspiring businesses to protect what matters most.